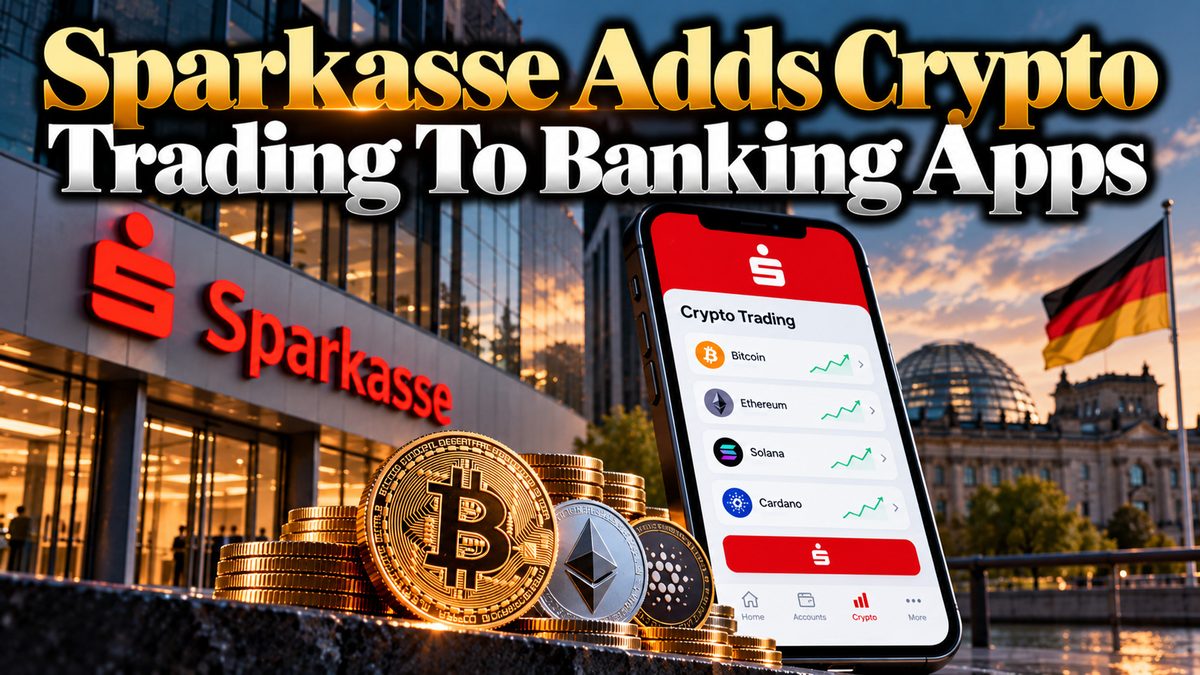
Sparkasse customers in Germany can now buy and sell five digital assets right inside their regular banking app, thanks to DekaBank's new integration. This is a big deal for mainstream adoption—millions of everyday savers who never touched crypto now have one-tap access. Still, convenience isn't the same as safety; these aren't self-custodied assets, so the usual bank-held risks apply. Worth watching how fast other traditional banks follow this playbook.
Sparkasse Adds Crypto Trading To Banking Apps
German savings banks under the Sparkassen umbrella are integrating crypto trading directly into their existing banking apps, as reported by BeInCrypto. The feature runs through DekaBank, the securities house that serves Sparkassen customers, and lets users buy and sell five digital assets without downloading a separate exchange app or opening a new account elsewhere.
For customers, this means crypto now sits next to checking accounts, savings, and everyday transfers in a single interface. The rollout is aimed squarely at people who have never traded crypto before, lowering the barrier to entry by putting the feature somewhere they already look every day.
Why This Matters For Adoption
Savings banks like Sparkasse are typically the first financial relationship many people have, often trusted for decades of routine banking rather than speculative investing. By embedding crypto trading into that familiar environment, DekaBank is effectively introducing digital assets to a much broader, less crypto-native audience than typical exchanges reach.
This kind of integration is different from a dedicated crypto exchange signing up new users. It reaches people who were never actively seeking crypto exposure but now encounter it as just another option inside an app they already trust. That distinction matters for how fast and how broadly crypto adoption can spread beyond existing enthusiasts.
Custody Risk Is Still The Catch
A key detail is that these assets are not self-custodied. In crypto, self-custody means holding your own private keys, giving you direct control over your coins without relying on a third party. When a bank or broker holds the assets on your behalf instead, you are trusting that institution's security, solvency, and policies rather than controlling the keys yourself.
This arrangement offers convenience and familiarity, but it reintroduces a layer of counterparty risk that self-custody is designed to avoid. Customers using this feature should understand that buying crypto through a banking app is not the same as holding it in a personal wallet, even though the buying and selling experience may feel just as simple as any other transaction in the app.
What It Means For Spot Traders
For spot traders, this development is mostly a signal about distribution and access rather than price action. More mainstream, non-crypto-native users gaining easy entry points can expand the overall pool of participants in the market over time, but that says nothing about where prices go next, and no outcome should be assumed from access alone.
Traders already active in crypto don't need to change their approach because of this news. Those who prefer holding spot positions and building them gradually, rather than reacting to short-term headlines, can treat this as one more data point on adoption trends. Anyone using a bank-integrated feature like this should also weigh the custody trade-off against the convenience before deciding how and where to hold their assets.
Watching For Copycats
It's reasonable to expect other traditional banks to watch how this rollout performs. If other institutions follow a similar playbook, embedding crypto trading into existing banking apps could become a broader trend among retail banks beyond Germany, something worth tracking as more details emerge.